Payday Loans in Singapore: What You Need to Know
Unexpected expenses can create a short-term cash shortage. For example, this includes urgent household expenses, medical bills, or other financial commitments such as Payday Loans.
If you are searching for Payday Loans in Singapore, understand how short-term borrowing works. Additionally, before deciding whether a loan is suitable for you, note the costs and repayment obligations.
Loans offered by licensed moneylenders in Singapore are regulated by the Ministry of Law’s Registry of Moneylenders (ROM). There are rules for Payday Loans and other loans, covering interest, fees, borrowing limits, and how licensed moneylenders grant loans.
This guide explains what people commonly mean by Payday Loans.
It covers borrowing from a licensed moneylender in Singapore, the costs to consider.
It also shows how to identify a licensed lender and what alternatives exist.
What Is a Payday Loan?
A payday loan generally refers to short-term borrowing intended to cover an immediate cash need, traditionally until the borrower’s next salary or payday.
People searching for payday loans in Singapore may also encounter terms such as short-term loans, cash loans, personal loans or loans from licensed moneylenders. These terms should not automatically be treated as identical products because repayment periods, eligibility criteria, costs and loan terms can differ between lenders and products.
Rather than focusing only on how quickly money may be available, borrowers should consider:
- the amount they actually need;
- the total amount they will have to repay;
- interest and applicable fees;
- the repayment schedule;
- whether repayments are affordable alongside existing expenses and debts; and
- whether another financial option would be more suitable.
The Registry of Moneylenders advises borrowers to consider alternatives before approaching a moneylender and to carefully assess whether they can meet the contractual terms based on their income and existing financial obligations.
How Do Payday Loans Work in Singapore?
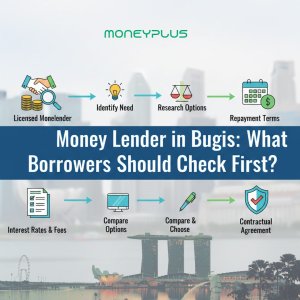
If you are considering a short-term loan from a licensed moneylender, there are several steps to understand.
1. Consider How Much You Actually Need
Start with the expense you need to cover rather than the maximum amount you might qualify to borrow.
Borrowing more than necessary increases the amount that must eventually be repaid.
2. Verify the Moneylender
Before providing personal information or proceeding with a loan, check the lender against the official Registry of Moneylenders list of licensed moneylenders in Singapore (Minlaw).
The Registry specifically recommends verifying both the lender’s physical address and website against its official list before visiting a lender’s website or premises.
3. Understand the Loan Terms
Before accepting a loan, understand:
- principal amount;
- interest;
- administrative fee;
- repayment dates;
- installment amounts;
- late-payment charges; and
- total repayment obligation.
Do not sign a blank or incomplete loan contract.
The Registry identifies granting a loan without properly explaining the terms and conditions or without providing the borrower with a copy of the loan contract as unacceptable practices.
4. Complete the Required Verification
A licensed moneylender cannot complete the entire loan transaction remotely.
The lender must meet the borrower in person at its approved place of business and perform physical face-to-face identity verification before granting the loan.
This distinction is especially important for people searching for a payday loan Singapore online or payday loans online.
Can You Get a Payday Loan Fully Online in Singapore?
You should be cautious when you see claims suggesting that a loan from a licensed moneylender can be completed entirely online without visiting the lender.
According to the Registry of Moneylenders, licensed moneylenders are required to meet borrowers in person at their approved place of business to conduct physical face-to-face identity verification before granting a loan.
A loan transaction performed fully online is not allowed.
Online facilities may still be used for preliminary inquiries or parts of the process where permitted, but they do not replace the required in-person verification before the loan is granted.
The Registry also warns about scammers and unlicensed moneylenders impersonating legitimate licensed lenders through websites, SMS, WhatsApp and social media.
Before proceeding, verify the lender’s details using the official ROM list rather than relying solely on a website or message you received.
How Much Can You Borrow From a Licensed Moneylender?
How much a person can borrow depends on factors including whether the loan is secured or unsecured, annual income and residency status.
According to the Registry’s borrower guidance, the aggregate maximum for unsecured loans across licensed moneylenders is:
| Annual income | Singapore Citizens & PRs | Foreigners residing in Singapore |
|---|---|---|
| Less than $10,000 | $3,000 | $500 |
| At least $10,000 but less than $20,000 | $3,000 | $3,000 |
| At least $20,000 | 6× monthly income | 6× monthly income |
For secured loans, different rules apply.
These are regulatory maximums, not amounts that every applicant will necessarily be offered or should borrow.
A borrower should consider affordability rather than treating the maximum borrowing limit as a target.
How Much Interest Can a Licensed Moneylender Charge?
Cost is one of the most important factors when comparing payday loans, payday advance loans or other short-term cash loans.
For loans subject to Singapore’s licensed-moneylender cost controls, the maximum interest rate is 4% per month.
If a borrower is late with a repayment, the maximum late interest rate is also 4% per month, and late interest may only be charged on the amount that is actually overdue.
Interest is calculated on a reducing principal balance rather than continuously on the original principal after principal repayments have been made.
What Fees Can a Licensed Moneylender Charge?
The rules also place limits on permitted fees.
For loans covered by these protections, a licensed moneylender may charge:
- an administrative fee of up to 10% of the loan principal when the loan is granted;
- a late fee of up to $60 for each month of late repayment;
- interest of up to 4% per month; and
- late interest of up to 4% per month on the amount that is overdue.
In addition, the total borrowing costs consisting of interest, late interest, the administrative fee and late fees cannot exceed an amount equivalent to the original principal of the loan.
Before signing a loan agreement, ask for the repayment terms to be clearly explained and make sure you understand the total amount you may need to repay.
Payday Loan vs Personal Loan in Singapore
| Factor | Short-term / payday-style borrowing | Personal loan |
|---|---|---|
| Typical purpose | Short-term or urgent expense | Broader personal financing needs |
| Loan duration | Often associated with shorter-term borrowing | May offer a longer repayment period |
| Provider | May include licensed moneylenders | Banks and other eligible lenders may offer personal loans |
| Costs | Depend on lender and applicable regulations | Depend on provider and product |
| Repayment | Check whether repayments fit your immediate budget | Longer repayment schedules may be available depending on product |
| What to compare | Total cost, fees, repayment dates and affordability | Interest/EIR, fees, tenure, installments and total repayment |
The name of the loan matters less than its actual terms.
When comparing a personal loan with a short-term loan, look at the total repayment amount, effective cost, repayment period and affordability, rather than choosing a product simply because approval appears faster.
How to Check Whether a Moneylender Is Licensed in Singapore
This deserves much more prominence than it has in your current article.
Before borrowing from a moneylender, visit the official Registry of Moneylenders and check the current list of licensed moneylenders.
Verify details such as the lender’s:
- registered business name
- approved business address
- license information and official website address.
Do not assume that a company is licensed simply because its website uses phrases such as “licensed lender,” “approved lender” or “legal moneylender.”
Scammers may create websites and social-media accounts designed to resemble legitimate licensed moneylenders.
How to Choose a Licensed Moneylender in Singapore guide here, followed by a prominent link to the official ROM list.
Watch Out for Loan Scams
Borrowers searching for urgent payday loans, fast payday loans online or a same-day loan in Singapore may be particularly vulnerable to offers promising immediate approval.
Urgency should not prevent you from verifying who you are dealing with.
The Registry warns that licensed moneylenders are not allowed to solicit loans through channels such as SMS, phone calls or social-media platforms. It has also warned about scammers asking victims to transfer money for supposed “GST fees” or “processing fees” before a loan is disbursed.
Be especially cautious if someone:
- contacts you unexpectedly offering a loan
- asks you to transfer money before receiving a loan
- claims the entire licensed-moneylender transaction can be completed remotely
- asks for your Singpass password
- asks to retain your NRIC, passport, work permit, ATM card or other personal identification documents; or
- asks you to sign an incomplete loan contract
The Registry’s borrower guidance specifically identifies several of these practices as unacceptable.

What to Check Before Taking a Short-Term Cash Loan
A short-term cash loan may solve an immediate cash-flow problem, but repayment becomes another financial commitment.
Before borrowing, ask yourself these questions.
Do I really need to borrow?
Consider whether the expense can be postponed, reduced or covered through another source.
How much do I actually need?
Borrow based on the necessary expense rather than the maximum available amount.
What is the total repayment?
Don’t focus solely on the amount you receive. Calculate what you are expected to repay, including permitted interest and fees.
Can I comfortably make every repayment?
Consider existing commitments such as rent, utilities, food, transport, insurance and other debts.
What happens if I pay late?
Understand the applicable late interest and fees before signing the contract.
Have I compared alternatives?
The Registry itself advises borrowers to consider other alternatives, including relevant financial-assistance schemes, before approaching a moneylender.
Alternatives to Payday Loans in Singapore
A payday-style or short-term loan is not necessarily the best solution for every urgent expense.
Depending on your circumstances, alternatives may include:
Personal Loans
A personal loan from a bank or another eligible provider may offer different interest rates, eligibility requirements and repayment periods.
Compare the total cost rather than assuming one type of loan is automatically cheaper.
Existing Credit Facilities
If you already have access to an appropriate credit facility, compare its cost and repayment conditions with taking out a new loan.
Payment Arrangements
For some bills, it may be possible to ask the service provider whether installments or a revised payment schedule are available.
Government or Community Financial Assistance
Depending on your circumstances and eligibility, financial-assistance schemes may be available.
The Registry specifically recommends considering other alternatives, including financial-assistance schemes offered by government agencies, before borrowing from a moneylender.
The appropriate choice depends on your financial situation, eligibility and ability to repay.
How to Use a Short-Term Loan Responsibly
If you decide that borrowing is appropriate after considering the alternatives, responsible borrowing can reduce the risk of repayment difficulties.
Borrow Only What You Need
A larger loan creates a larger repayment obligation. Base the amount on the expense you need to cover.
Read the Contract Before Signing
Make sure you understand the interest, fees, repayment schedule and consequences of late payment.
Never sign a blank or incomplete contract.
Keep Your Documents and Receipts
The Registry advises borrowers to ensure they receive receipts for repayments and to retain statements of account and payment receipts as evidence.
Pay According to the Agreed Schedule
Late payments can result in additional costs. If you anticipate repayment difficulties, address the situation early rather than ignoring the problem.
Why Borrowers Consider MoneyPlus
MoneyPlus Capital Pte Ltd provides loan services in Singapore.
When considering Moneyplus or any moneylender borrowers should independently verify the lender’s current license status, approved business address and website against the official Registry of Moneylenders list before proceeding.
At MoneyPlus, borrowers can request information about available loan options, eligibility requirements, repayment arrangements and applicable costs before deciding whether to proceed.
- How to Choose a Licensed Moneylender in Singapore
- Personal Loan Singapore
- Fast Urgent Cash Loan Singapore

Frequently Asked Questions About Payday Loans in Singapore
1. What is a payday loan?
A payday loan Singapore generally refers to short-term borrowing intended to cover an immediate cash need, traditionally until or around the borrower’s next payday.
In Singapore, focus on the actual lender, loan terms, repayment schedule and applicable regulations rather than the product label alone.
2. Are payday loans legal in Singapore?
Moneylending is regulated in Singapore. If you are considering borrowing from a moneylender, verify that the company appears on the official Registry of Moneylenders list and understand the terms of the specific loan being offered.
3. Can I get a payday loan fully online in Singapore?
Not from a licensed moneylender as a fully remote transaction. Licensed moneylenders must conduct physical face-to-face identity verification at their approved place of business before granting a loan.
You may encounter online inquiry facilities, but they do not remove this in-person requirement.
4. How much interest can a licensed moneylender charge?
For loans subject to Singapore’s licensed-moneylender cost controls, the maximum interest rate is 4% per month. The maximum late interest rate is also 4% per month and applies to amounts that are actually overdue.
5. What fees can a licensed moneylender charge?
Permitted costs include an administrative fee of up to 10% of the principal when the loan is granted and a late fee of up to $60 for each month of late repayment, subject to the applicable rules. Total permitted borrowing costs are also capped.
6. How can I tell if a moneylender is licensed?
Check the official list of licensed moneylenders published by the Registry of Moneylenders. Verify the business name, approved address and website against the official list rather than relying on information sent to you through messages or social media.
7. Can foreigners borrow from licensed moneylenders in Singapore?
Foreigners residing in Singapore may be able to borrow, subject to eligibility, assessment and the applicable borrowing limits. The regulatory maximum for unsecured borrowing varies according to annual income.
8. Can I get a same-day loan in Singapore?
Processing time depends on the lender, the borrower’s circumstances, required documents and necessary checks. Avoid treating “same-day” as a guarantee.
Most importantly, a licensed moneylender still has to perform the required in-person identity verification before granting the loan.
9. What happens if I cannot repay on time?
Late repayment may result in permitted late interest and late fees under the loan agreement and applicable regulations. If you are experiencing repayment difficulties, review your contract and address the issue promptly rather than allowing missed payments to accumulate.
10. Should I choose a payday loan or personal loan?
There isn’t one answer for every borrower. Compare the total borrowing cost, repayment period, installment amount, eligibility requirements and your ability to repay.
If another suitable and less costly option is available, consider it before taking a short-term loan.
Conclusion
People searching for a payday loan in Singapore are often trying to solve an immediate cash-flow problem. Speed, however, should not be the only consideration.
Before taking a short-term loan, understand the interest and fees, calculate whether you can afford the repayments, compare alternatives and verify that any moneylender you deal with is listed by Singapore’s Registry of Moneylenders.
Be particularly careful with payday loans online, unsolicited loan offers and anyone claiming that a licensed moneylender can grant a loan through a completely remote process.
If you are considering a loan from MoneyPlus, ask about the applicable terms, costs and repayment schedule before making a decision, and independently verify the company’s current license information through the official Registry of Moneylenders.
MoneyPlus Capital Pte Ltd
Hours: 11:00 AM – 6:30 PM, Monday–Saturday
Closed Sundays & Public Holidays