Understanding Licensed Money Lenders in Singapore
Living expenses, unexpected bills and short-term financial emergencies can place pressure on household budgets in Singapore. For people with lower or less predictable incomes, finding a suitable source of credit can be especially challenging.
A licensed money lender in Singapore may provide personal loan options to borrowers who need additional funds for genuine financial needs. However, borrowing should always be approached carefully. The amount borrowed, interest charges, fees and repayment schedule should fit comfortably within the borrower’s financial situation.
Borrowers should also verify that they are dealing with a properly licensed lender before signing any agreement.
At Moneyplus Capital, borrowers can explore different loan options and learn more about the application process before deciding whether borrowing is suitable for their circumstances.
Can Low-Income Borrowers Get a Personal Loan in Singapore?
Having a lower income does not automatically prevent someone from applying for a personal loan.
Licensed moneylenders generally assess each application according to factors such as income, existing financial commitments, supporting documents and the borrower’s ability to repay.
People searching for a personal loan for low income Singapore should therefore focus not only on whether they can qualify, but also on whether the repayment amount is manageable.
A personal loan in Singapore may be used for various legitimate expenses, such as:
- unexpected household expenses
- medical costs
- urgent repairs
- temporary cash-flow shortages
- family expenses
- other essential personal needs
The important principle is to borrow only what is necessary and what can reasonably be repaid.
The Ministry of Law advises borrowers to consider their income and existing obligations carefully before committing to any loan contract. Borrowers are legally required to meet the terms of the loan agreement once they enter into it.
Quick and Fast Money Lenders in Singapore: What Should Borrowers Check?
Searches for quick money lenders, fast money lenders, instant money lenders and urgent money lenders often come from people facing time-sensitive financial situations.
Speed can be useful, but it should never be the only factor considered when choosing a lender.
A borrower who needs money urgently should still check:
- whether the lender is properly licensed
- the interest rate
- all applicable fees
- the repayment period
- the amount of each installment
- the total amount repayable
- whether the loan fits the borrower’s budget
Borrowers looking for help with urgent expenses can read more about fast and urgent cash loan options in Singapore.
It is also important to understand that a fast application process does not mean guaranteed approval. Licensed lenders are still expected to conduct proper checks before granting a loan. The Ministry of Law specifically identifies granting loans without proper due diligence as an unacceptable practice.
How Much Can Low-Income Borrowers Borrow?
Singapore has regulated borrowing limits for unsecured loans from licensed moneylenders.
According to the Ministry of Law, the maximum aggregate unsecured amount that may be borrowed across all licensed moneylenders depends on annual income and residency status.
| Annual Income | Singapore Citizens / PRs | Foreigners Residing in Singapore |
|---|---|---|
| Less than $10,000 | $3,000 | $500 |
| At least $10,000 but below $20,000 | $3,000 | $3,000 |
| $20,000 or more | Up to 6× monthly income | Up to 6× monthly income |
These are maximum regulatory limits, not guaranteed loan amounts.
A lender may approve a smaller amount or decline an application after considering the borrower’s circumstances and ability to repay.
For low-income borrowers in particular, taking the maximum available amount may not necessarily be the best financial decision. A smaller loan with affordable repayments may be more manageable.
What Interest Rates Can a Licensed Money Lender Charge?
Interest rates are one of the most important considerations when comparing loan options.
Licensed moneylenders in Singapore may charge a maximum interest rate of 4% per month. This cap applies regardless of the borrower’s income and whether the loan is secured or unsecured.
If a payment is late, late interest is also capped at 4% per month, and it may only be applied to the amount that is overdue.
Borrowers should therefore ask for a clear explanation of:
- the interest rate
- how interest is calculated
- the repayment schedule
- the total repayment amount
Do not assess a loan only by the size of the monthly installment. A longer repayment period can affect how much is ultimately paid.
What Fees Can Licensed Moneylenders Charge?
Borrowers should also understand the fees that may apply.
Under current Ministry of Law rules, licensed moneylenders may charge:
- an administrative fee of up to 10% of the principal when the loan is granted
- a late fee of up to $60 for each month of late repayment
- court-ordered legal costs where applicable
The combined interest, late interest, administrative fee and late fees cannot exceed an amount equivalent to the original principal of the loan.
This is why borrowers should look at the total cost of borrowing, not just the amount they receive initially.
Small and Short-Term Loans in Singapore
Some borrowers may not need a large loan. They may simply require a smaller amount to deal with a temporary financial gap.
People searching for low interest small loans, short-term money lenders or small personal loans should still compare the same key factors as they would for a larger loan.
These include:
- interest
- administrative fees
- repayment frequency
- loan duration
- late-payment charges
- total repayment amount
A smaller loan is not automatically inexpensive.
Borrowers should calculate whether they can comfortably meet each repayment while continuing to pay for essentials such as housing, food, utilities and transport.
Can Someone With Bad Credit Apply for a Personal Loan?
A weak credit history can make borrowing more difficult, but it does not necessarily mean that every application will be rejected.
Licensed moneylenders may consider several factors when assessing an application rather than relying on only one piece of financial information.
Borrowers researching a personal bad credit loan in Singapore should be prepared to provide accurate information about their income and existing financial commitments.
Most importantly, borrowers should avoid taking on another loan merely to postpone an existing financial problem unless they have a clear and sustainable repayment plan.
A loan should improve short-term cash flow without creating an unaffordable longer-term obligation.
Can an Unemployed Person Apply for a Loan in Singapore?
Searches such as loan for unemployed Singapore, cash loan for unemployed Singapore and personal loan for unemployed are common among people experiencing a temporary loss of employment or irregular income.
Being unemployed does not itself guarantee approval or rejection.
A lender may need to assess whether the applicant has another verifiable source of income or a realistic ability to make repayments.
Possible sources of income may include, depending on the applicant’s circumstances:
- freelance earnings
- self-employment income
- commissions
- contract work
- other verifiable recurring income
Applicants should provide accurate information and should not take on a repayment commitment if they do not have a realistic way of meeting it.
Loans marketed or searched for as “no income loans” should be approached particularly carefully. Approval should never be assumed simply because a website or advertisement suggests fast access to money.
Self-Employed Borrowers and Irregular Income
Self-employed individuals can face a different challenge because their monthly income may fluctuate.
Before applying for an urgent cash loan, self-employed borrowers should calculate repayments against a conservative estimate of their average income rather than their strongest earning month.
They should also prepare any financial records requested by the lender to demonstrate their income.
Borrowing based on realistic cash flow can reduce the risk of struggling with repayments during quieter months.
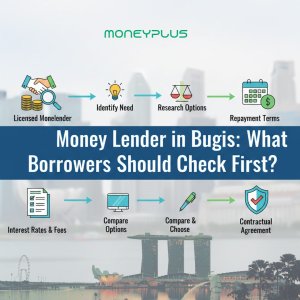
How to Apply for a Personal Loan
The exact application process can vary depending on the lender, but borrowers should expect to provide identity and financial information so that their application can be assessed properly.
A typical process may involve:
- Reviewing the loan type and estimated repayment amount.
- Preparing identification and relevant income documentation.
- Submitting accurate personal and financial information.
- Allowing the lender to assess eligibility and repayment ability.
- Reviewing the loan contract carefully.
- Asking questions about anything that is unclear.
- Signing only after understanding the repayment schedule, interest and fees.
Borrowers who are ready to enquire can visit the Moneyplus loan application section.
Never give a lender your Singpass password. The Ministry of Law specifically warns borrowers about lenders asking for Singpass user IDs or passwords.
How to Check Whether a Moneylender Is Licensed
Before borrowing, verify the lender against the official Registry of Moneylenders list.
Do not assume a business is licensed simply because its website looks professional or because someone contacts you claiming to represent a lender.
Singapore’s Ministry of Law advises borrowers not to borrow from unlicensed moneylenders and to check the official list of licensed moneylenders before proceeding.
Borrowers should also be cautious if a lender:
- asks for a Singpass password
- keeps an NRIC, passport or other personal identification document
- asks the borrower to sign a blank or incomplete contract
- does not clearly explain the loan terms
- fails to provide a copy of the loan contract
- offers a loan without carrying out appropriate checks
These are warning signs identified in official Ministry of Law borrower guidance.
Be Careful With Unsolicited Loan Messages
Borrowers searching for quick money should be especially alert to unsolicited advertisements.
Licensed moneylenders in Singapore are permitted to advertise only through specific channels, including their own websites, their business premises and approved business or consumer directories.
The Ministry of Law states that licensed moneylenders are not permitted to advertise through SMS, and borrowers are advised not to respond to unsolicited loan advertisements sent through prohibited channels.
Choosing a lender should begin with verification, not with responding to an unexpected message.
Payday Loans and Short-Term Cash Needs
Some borrowers may need funds to cover expenses before their next salary payment.
Before considering a payday loan in Singapore, borrowers should work out whether the next salary payment can realistically cover both the loan repayment and normal living expenses.
Using future income to solve today’s cash-flow problem can create another shortage if too much of the next salary is committed to debt.
A short repayment period therefore needs the same careful budgeting as a longer personal loan.
Loans for Unexpected Medical Expenses
Medical expenses can arise unexpectedly and may put pressure on household finances.
Where other payment or assistance options are not sufficient, some borrowers may consider medical loan options in Singapore to manage eligible healthcare-related expenses.
Before borrowing, compare the amount required against existing savings, available assistance schemes and the repayment commitment involved.
The Ministry of Law also recommends considering other forms of financial assistance before approaching a moneylender.
Debt Consolidation and Multiple Loan Repayments
Managing several separate debts can make budgeting difficult.
A debt consolidation loan may help some borrowers reorganise multiple financial obligations into a more structured repayment arrangement.
However, consolidation does not automatically mean that borrowing becomes cheaper.
Borrowers should compare:
- the remaining balance on existing debts
- the new interest rate
- fees
- repayment duration
- monthly installments
- total repayment amount
The objective should be to make repayment more manageable without unnecessarily increasing the total cost of debt.
Other Personal Financing Needs
Not every personal loan is taken for an emergency.
Depending on individual circumstances, borrowers may also explore financing for significant planned expenses.
For example, Moneyplus provides information about:
Wedding loan options in Singapore for couples considering financing for wedding-related expenses.
Travel loan options for borrowers considering how to manage eligible travel expenses.
Bridging loan options for borrowers dealing with certain short-term financing gaps.
Whatever the purpose, the same principle applies: the repayment commitment should be affordable after essential living expenses and existing debts are taken into account.
How to Choose a Moneylender in Singapore
Borrowers often search for the best moneylender in Singapore, but there is no single loan that is automatically best for every applicant.
The more useful approach is to compare lenders according to factors that affect the individual borrower.
These include:
- license status
- clear loan terms
- interest and fees
- repayment period
- customer service
- transparency
- affordability of installments
- total repayment amount
You can read more about what to consider when comparing moneylenders in Singapore.
A borrower should never feel pressured into accepting a loan before understanding the contract.
The Ministry of Law advises borrowers to shop around and compare terms rather than rushing into a loan commitment.
Responsible Borrowing for Low-Income Households
For borrowers with limited disposable income, repayment affordability is particularly important.
Before applying for a loan, create a simple monthly budget that includes:
- take-home income
- rent or housing costs
- utilities
- food
- transport
- insurance
- existing debt repayments
- family commitments
- emergency savings
Only the amount remaining after essential commitments should be considered when assessing whether a new repayment is affordable.
Borrowing can help manage a temporary financial gap, but repeatedly borrowing to cover normal monthly expenses can indicate a deeper cash-flow problem.
Where possible, borrowers should gradually build an emergency fund so that future unexpected expenses do not always require credit.
What to Do After Receiving a Loan
Responsible borrowing continues after the loan is approved.
Borrowers should:
- check that the loan amount received is correct
- keep a copy of the loan agreement
- make repayments by the agreed due dates
- retain receipts for every repayment
- check statements for accuracy
- contact the lender early if repayment difficulties arise
The Ministry of Law states that borrowers should receive receipts for repayments and account statements, and should retain these documents as evidence of payment.
Frequently Asked Questions About Licensed Money Lenders in Singapore
How do I know whether a money lender is licensed?
Check the official Registry of Moneylenders maintained by Singapore’s Ministry of Law before taking a loan. Do not rely solely on an advertisement or message claiming that a lender is licensed.
Can low-income borrowers apply for personal loans?
Yes, low-income individuals may apply, but approval and the amount offered depend on the lender’s assessment and applicable borrowing limits. Borrowers should focus on affordability rather than simply trying to obtain the maximum possible amount.
What is the maximum interest rate charged by a licensed money lender?
The maximum permitted interest rate is 4% per month. Late interest is also capped at 4% per month and may only be charged on the amount that is overdue.
Are fast or urgent loans guaranteed?
No. A fast application or assessment process does not guarantee approval. A licensed lender should still assess the application and supporting information before deciding whether to grant the loan.
Can someone with bad credit apply?
An applicant with a weaker credit history may still enquire about borrowing, but approval is not guaranteed. Borrowers can learn more about personal loan options for bad credit.
Can unemployed borrowers get a loan?
An unemployed applicant’s circumstances need to be assessed individually. A lender may consider other verifiable income and the applicant’s ability to repay. Borrowing should not be undertaken without a realistic repayment plan.
Should I choose the fastest money lender available?
Not solely because of speed. Verify the lender’s license and compare interest, fees, repayment terms and total repayment cost before making a decision.
Is a smaller loan always cheaper?
Not necessarily. Borrowers should compare interest, fees and repayment terms even when borrowing a small amount.
Conclusion – Borrowing Responsibly From a Licensed Money Lender in Singapore
A licensed money lender in Singapore can provide another borrowing option for people dealing with short-term financial needs, including borrowers with lower or irregular incomes.
However, quick access to funds should never replace careful decision-making.
Before taking any personal loan, confirm that the lender is licensed, understand the interest and fees, review the repayment schedule and make sure the installments are sustainable within your budget.
Borrow only what you need and can realistically repay.
To learn more about available loan options, visit Moneyplus Capital, or read more about Moneyplus Capital.
For inquiries, contact Moneyplus Capital or visit the online loan application section.
Moneyplus Capital
371 Beach Road, #02-25 City Gate
Singapore 199597
Tel: +65 6904 7073
Opening Hours:
11:00 AM – 6:30 PM, Monday to Saturday
Closed on Sundays and Public Holidays